myEquifax

Screenshots
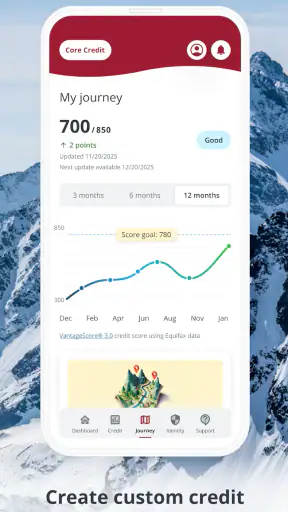
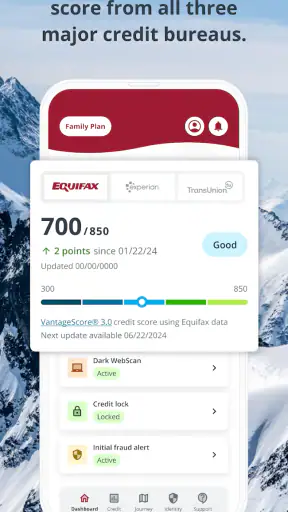
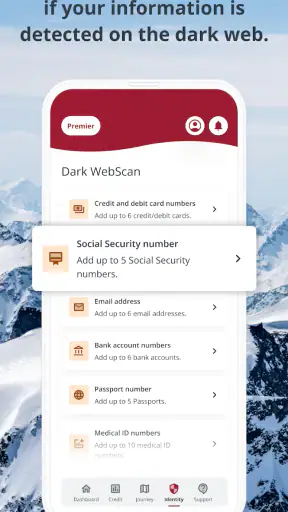
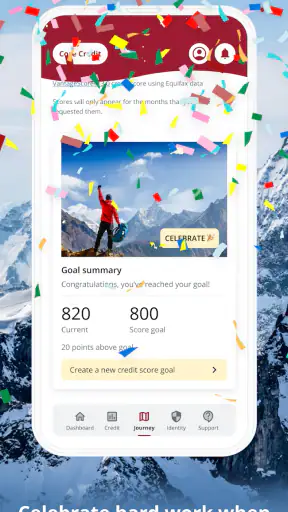
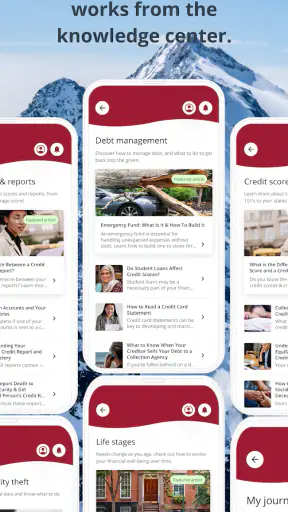
Details
- Rating
- 988.00 reviews
- Version
- 1.11.0
- Developer
- Equifax Incorporated
Analysis by Norviv
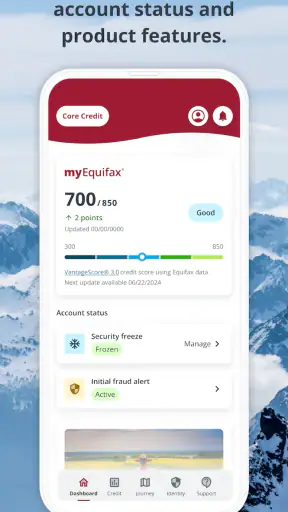
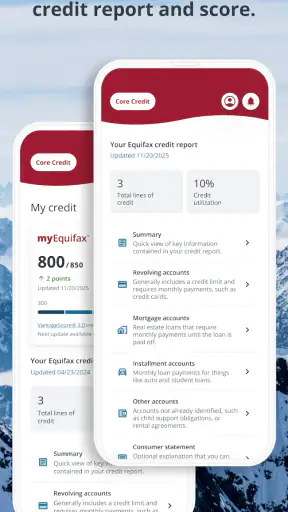
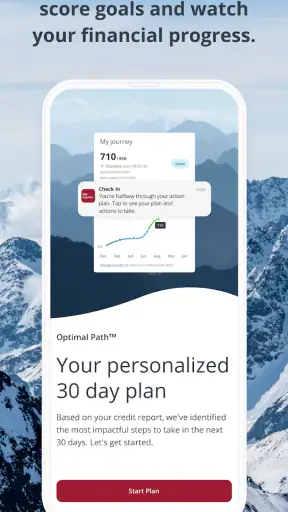
Managing credit is rarely difficult because of one complicated task. It is difficult because the important details are spread across reminders, emails, account pages, and paperwork, while the consequences of missing something can last for a long time. myEquifax is a free finance app from Equifax Incorporated that aims to put the beginning of that credit journey in a more convenient mobile setting. I spent time looking at it as an everyday credit companion rather than treating it like a full personal-finance dashboard, and that distinction matters.
My overall impression is that it makes the most sense for someone who wants a direct way to stay connected with Equifax from a phone. It is less convincing as a complete replacement for every credit tool a person might use. The app is currently at version 1.11.0, supports Android 8.0 and later, and carries an Everyone age rating. Those details make it accessible to a broad audience, but accessibility alone does not make a finance app useful; the real question is whether it helps you turn credit information into better habits.
How myEquifax fits into a real credit routine
The app’s store summary, “Start your credit journey,” gives a good clue about its intended audience. I would not approach it expecting a budgeting app with extensive spending categories, investment tracking, or a broad collection of financial accounts. Its natural role is narrower: helping users engage with their Equifax credit experience from a mobile device.
That narrower focus can be a strength. When I want to check a credit-related detail, I do not necessarily want to open a large financial app and sort through banking, bills, subscriptions, and investments first. A dedicated Equifax app can reduce that mental clutter. For a person building credit for the first time, reviewing information in one familiar place may also make the process feel less intimidating.
A realistic example is someone preparing to rent an apartment. Before submitting an application, they may want to review their credit situation, check that their personal information looks familiar, and make sure they understand what they are presenting to a landlord. The app can fit into that preparation as a quick checkpoint. It should not be treated as a guarantee that a landlord, lender, or insurer will make a particular decision, but it can help the user become more aware of their credit position before an important application.
I also see value for people who are trying to establish a routine rather than reacting only when they need a loan. Opening the app at a regular, sensible interval can encourage users to notice changes and keep their credit responsibilities in mind. The important word is “sensible”: checking repeatedly throughout the day will not improve a credit profile, and the app should support calm monitoring rather than anxiety.
The current experience is best for focused checking
In my experience, the strongest reason to use myEquifax is focus. It is designed around a specific relationship with Equifax, so the experience feels more relevant than a generic financial organizer when the question is specifically about Equifax credit information. That makes it easier to decide what to do next: review, understand, follow up, or simply return later.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
There is also a practical privacy advantage to keeping a credit-focused task separate from a general money-management app. Some users prefer not to connect every bank account and card to one service. Choosing a dedicated app can mean a smaller, more intentional digital routine. That does not remove the need to read account prompts carefully or protect the phone, but it gives users another way to organize their financial life.
The trade-off is that a focused app cannot automatically become a complete financial command center. If your main goal is to compare monthly spending, build a detailed household budget, track investments, or see several credit bureaus together, you may still need another application or service. myEquifax is better understood as one part of a credit workflow than as the entire workflow.
What the recent version tells me about product direction
The current release, version 1.11.0, shows that the app is an actively maintained product rather than a forgotten utility. It was released on April 25, 2025, giving the app a relatively recent starting point for users evaluating it today. I would interpret that as evidence of a product still being shaped, not proof that every desired feature has already arrived.
That distinction is important. A version number can tell me where the app is in its development, but it does not by itself promise a particular feature, performance improvement, or future release. I would therefore judge the current app on what it does now and treat future updates as something to evaluate when they appear, not as a reason to overlook present friction.
The public response is encouraging: myEquifax has an average rating of 4.6 from around eleven thousand ratings, with close to a thousand written reviews. It has also passed half a million installs. Those figures suggest that many people find the app useful enough to keep installed or rate positively, but they are not a substitute for checking whether its purpose matches your own. A person looking for credit monitoring may be satisfied, while someone expecting a complete banking app could still be disappointed.
What existing Equifax users should expect
If you already use Equifax through a browser, the mobile app is most useful when convenience changes your behavior. A phone-based experience can make it easier to check in at the moment a credit question comes up, rather than postponing it until you remember to sit at a computer. That small reduction in effort can matter when you are trying to build a regular habit.
However, I would not install it expecting the app to replace every web-based task. Financial services often divide functions between mobile and browser experiences, and a phone interface naturally favors quick review over lengthy investigation. If you need to work through a complicated dispute, compare documents, or carefully read extensive account information, a larger screen may still be more comfortable.
My practical advice is to use the app for awareness and the broader Equifax experience for deeper work when necessary. That two-step approach avoids a common mistake: treating a mobile shortcut as though it were the only place where every credit issue must be resolved.
A useful workflow before a major application
One of the less obvious ways to get value from a credit app is to use it before you need it, not during the final minutes before submitting an application. I would open myEquifax well ahead of a planned rental, vehicle-finance, or card application, review what is available, and write down any question that needs more attention. The goal is to create time for follow-up rather than discovering a concern at the worst possible moment.
A second helpful habit is separating observation from action. Seeing a change does not automatically mean that something is wrong. I would first compare the information with my own records, then decide whether the issue requires contacting Equifax, a lender, or another responsible organization. This prevents a rushed response based on a misunderstanding and makes the app a starting point for investigation rather than a source of instant conclusions.
A third is to keep a simple personal record of important dates and account activity outside the app. A credit app can help you notice information, but it should not be your only memory system. If you are disputing an entry or waiting for an update, keeping your own notes can make conversations and follow-up much clearer.
Where the app still feels limited
The biggest limitation is scope. myEquifax is not the right choice if you want one screen containing every part of your financial life. It is not a budgeting replacement, and I would not choose it as my only tool for tracking cash flow or planning household spending. A general finance app may be better for those jobs, especially if you need categories, recurring expenses, and broader account aggregation.
It may also be a poor fit for users who want an all-bureau view. Credit information can differ between bureaus, and focusing on Equifax alone may not answer every question about your overall credit picture. If you are preparing for a major financial decision and need a wider comparison, another service designed for multi-bureau monitoring could be more suitable.
There is a second kind of friction that comes from the subject itself. Credit information is personal and sometimes stressful. Even a well-designed app cannot make an unfamiliar entry instantly understandable, and a quick mobile screen may not provide enough room for context. I would avoid making a decision based on a single number or brief status message. Use the app to identify what deserves attention, then read the available explanation and follow the appropriate support route.
Finally, a positive rating does not mean every user will have the same experience. Around eleven thousand ratings and more than half a million installs show meaningful adoption, but people arrive with different account histories, devices, expectations, and reasons for using the app. I would consider the rating reassuring, not decisive.
Who should install it, and who should skip it
I would recommend myEquifax to a new credit user who wants a direct, focused starting point and prefers handling routine checks on a phone. It is also a sensible option for an existing Equifax user who often forgets to check credit information because the browser experience feels like too much effort. The free price removes a basic barrier to trying it, which is useful when you are still deciding whether a dedicated credit routine will become part of your life.
I would be more cautious about recommending it to someone who already has a comprehensive financial system and wants no additional app. If your current service already gives you the exact Equifax access and workflow you need, installing another app may add little beyond convenience. Likewise, a person seeking detailed budgeting, investment tools, or a combined view of several bureaus should look for a product built around those priorities instead.
Parents and younger users should also remember that an Everyone rating describes general audience suitability, not financial independence. Credit decisions still require care, and a simple interface should not encourage anyone to share credentials casually or treat credit information as entertainment. I would use a secure device, review sign-in prompts carefully, and avoid checking sensitive details on a public or shared phone.
Questions I would ask before making it part of my routine
The first question is whether it costs anything to try. myEquifax is free, so the initial decision is mainly about usefulness and trust rather than an upfront purchase. That does not mean every possible credit-related service in the wider Equifax ecosystem should be assumed to have identical terms; I would still read any in-app description before activating an optional service.
The second question is whether an older phone can run it. The minimum requirement is Android 8.0, so users on that version or a newer one meet the stated operating-system threshold. I would still keep the phone updated where possible, because a finance app deserves a device with current security support, not merely the oldest compatible software.
The third question is whether the app is suitable for a dispute or serious error. My answer is that it can be a useful place to notice and organize a concern, but I would not assume that a quick in-app view replaces the formal resolution process. For a significant discrepancy, gather your records, read the relevant instructions, and use the official route offered for that situation.
The fourth question is whether the app can replace a credit adviser. It cannot replace personal financial judgment. A screen can help you understand information, but it cannot know your complete goals, income, obligations, or tolerance for risk. For a complicated borrowing decision, I would use the app as one source of information and seek appropriate independent guidance when needed.
What I would watch in future updates
Because the app is at version 1.11.0 and began its current release history in 2025, I would pay attention to how Equifax Incorporated handles the next stage of refinement. The most valuable improvements would be the ones that make credit information easier to understand without turning the app into a noisy stream of alerts. Clear explanations, dependable navigation, and a straightforward path from noticing a concern to knowing the next step would matter more to me than decorative changes.
I would also watch how well the mobile experience supports users who need to move from quick checking to deeper account work. A good credit app should make the boundary clear: what can be handled conveniently on a phone, and when the user should move to a fuller support or web process. That clarity would reduce frustration and help people avoid assuming that a short status view tells the whole story.
Another thing worth watching is whether the app continues to serve beginners without becoming too basic for experienced users. The phrase “start your credit journey” points toward accessibility, and that is valuable. But returning users also need reasons to keep the app installed. The best evolution would preserve the simple entry point while adding more useful context and control for people who have developed a regular credit-monitoring habit.
My final take on the mobile credit companion
After reviewing myEquifax as a finance app rather than a general money manager, I see a clear and useful role for it. It gives Equifax users a free mobile doorway into their credit routine, works on Android 8.0 and later, and has already attracted a substantial audience with an average rating of 4.6. The current version feels like a product worth considering, especially if convenience is the difference between checking your credit occasionally and paying attention consistently.
My recommendation comes with boundaries. I would use it to stay aware, prepare for important applications, and investigate questions early. I would not use it as my only budgeting tool, my only view of credit across all bureaus, or a replacement for careful financial judgment. If those limits match your expectations, myEquifax is a practical way to make credit awareness part of an ordinary phone routine. If you need a complete financial dashboard, a broader alternative will probably serve you better.
For me, the app’s real value is not that it promises to solve every credit problem. It is that a focused, free tool can lower the effort required to begin paying attention. Used calmly and alongside your own records and decision-making, it can be a useful starting point rather than another financial app competing for attention.
Frequently Asked Questions
01What is myEquifax, and what can I use it for?
myEquifax is Equifax’s mobile and online service for accessing information related to your credit profile. Depending on your country and account type, it may let you review your credit report, check available credit scores, receive monitoring alerts, manage identity-protection features, and find guidance when something appears unfamiliar. The exact tools and information can vary by region and subscription.
02Is myEquifax free to download and use?
Downloading the myEquifax app is generally free, but not every feature is necessarily included at no cost. Some users may receive access to basic account information or limited credit-report services, while enhanced monitoring, identity protection, alerts, or additional reports may require a paid plan. Before subscribing, carefully review the price, renewal terms, trial conditions, and services included in your region.
03Is my personal and financial information safe in myEquifax?
myEquifax handles highly sensitive information, including identity details and credit data, so security is an important part of using the service. The app may support password protection, device authentication, verification codes, and other safeguards. Even so, users should install it only from an official app store, keep the app and operating system updated, avoid sharing login codes, and contact Equifax through official channels if suspicious activity occurs.
04Can myEquifax help me detect identity theft or incorrect information?
myEquifax can help you review credit-related information and, where available, receive alerts about certain changes or activity associated with your profile. This may make it easier to notice unfamiliar accounts, inquiries, or personal details. However, monitoring is not a guarantee that every form of fraud will be detected immediately. If you find an error or possible identity theft, follow Equifax’s dispute and fraud-reporting procedures promptly.
05What should I do if I cannot log in or the information in myEquifax is wrong?
If you cannot access your account, use the official password-reset or account-recovery options rather than links from unsolicited messages. Check that your personal details match Equifax’s records and that the app is updated. For incorrect credit information, use the dispute process provided inside the service or on Equifax’s official website. If the issue continues, contact customer support and keep records of your communications and submitted documents.


